Under the new vat act of 2026, employees are charged vat on the basis of “payable provision of catering services” for their own canteens, as follows:
I. Rules of access and application of treatment
An enterprise collects food at a cost (e. G., employees pay $5 per meal) as a “repayable service” and is subject to vat。
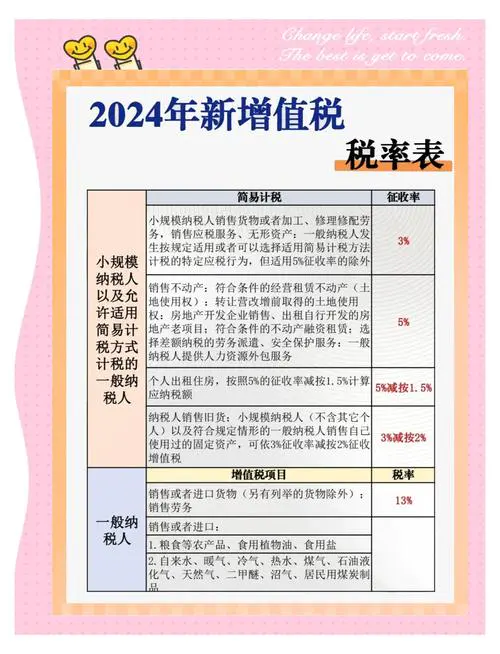
Taxes are taxable on the basis of the amount actually received。
Formula: discharge tax = total collection ÷ (1+ rate) x rate。
Example: if an employee pays $5 per meal and collects $100,000 (including taxes) quarterly, the tax is paid = 100,000 ÷ (1+6 per cent) x 6 per cent ≈0. 57 million。
Processing of imported taxes:
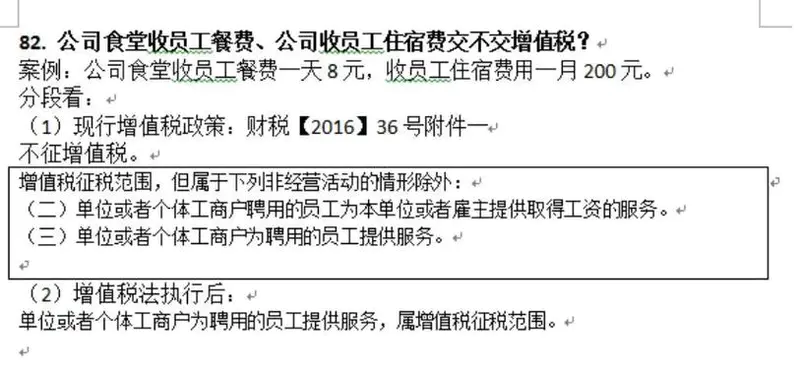
Expenditure on the purchase of food items, equipment, etc. In canteens, which is earmarked for free benefits for employees (company subsidy component), is not offset by the amount of tax
For reimbursable services (employees ' fee component), the required credit is payable。
Example: the canteen canteen purchase foods for which an advance tax of $0. 06 million (which can be clearly distinguished from paid services) is actually subject to vat = $0. 57 million-0. 06 million = $0. 03 million (which can be set aside or refunded if the advance exceeds the sale)。
Iii. Declarations and account processing requirements: no separate vat invoices are required, and businesses can report revenues and pay taxes in the vat returns under the heading “no invoiced sales”. Income accounting: the revenue from meals is charged to taxable income, distinguishing between self-employment and outsourcing:
(a) self-employed canteens: taxed under the above-mentioned rules, the amount of the revenue from procurement expenditure is deducted by purpose
Outsourcing canteens: enterprises are required to obtain compliance invoices for the payment of fees, which are recorded under the “dinning services” tax。
Mixed-use accounting: if a canteen provides free meals (corporate subsidies) and a fee (employees ' fees) at the same time, the income, costs and revenue tax for both types of business will need to be accounted for separately. The absence of separate accounting may result in the loss of tax-exempt preferences (e. G., the transfer of free partial payments required). Iv. Compliance recommendations to combo the cafeteria operating model to clarify the accounting boundaries between free and fee-based scenarios; to prioritize suppliers that can provide compliance invoices to avoid cost deductions that cannot be made before taxes due to the absence of instruments; and to adjust the benefit system (e. G., by consolidating meal subsidies into salary payments) in tandem with the impact of personal income tax。