


How do you figure out how much you can borrow from your own pool? 2026 full scheme for calculating the provident fund loan lines, formulae, scale of limits
I. What is a provident fund loan and why does it have to be measured in advance
Provident fund loan base schematic
Many home buyers who are ready to buy a house give preference to a provident fund loan, the central reason being that the interest rate on a provident fund loan is much lower than that on a commercial mortgage and saves a large amount of interest. Most buyers, however, do not know how to calculate the amount of their own equity loans, but wait to see the house and pay a down payment before they find that the amount is insufficient and are forced to convert into a commercial loan or a combination of loans to disrupt the purchase plan。
Many home buyers who are ready to buy a house give preference to a provident fund loan, the central reason being that the interest rate on a provident fund loan is much lower than that on a commercial mortgage and saves a large amount of interest. Most buyers, however, do not know how to calculate the amount of their own equity loans, but wait to see the house and pay a down payment before they find that the amount is insufficient and are forced to convert into a commercial loan or a combination of loans to disrupt the purchase plan。
Provident fund loans, which are paid by employees of the housing provident fund, apply to the provident fund management centre for policy loans at low interest rates when purchasing their own housing. The amount of the provident fund loan is not the type of loan sought, it is a comprehensive multi-conditional determination mechanism, which is subject to conditions such as the amount of the deposit base, the amount of the deposit balance, the time of deposit, the total price of the house, the local maximum loan limit, the amount of the personal letter, etc., and takes the minimum value from the results of the calculations as the final creditable amount。
Here is a core professional rule: each city has a policy of independence, with very different calculations, ceilings and no nationally uniform fixed formula. This paper describes the four measurement logics of the mainstream in the country, with reference tables, examples of calculations, and separate rules for singles, couples, first suites, second suites, and one step at a time to measure and plan the budget for the purchase of housing。
Ii. Provident fund loan lines 4 large core limits (final amount to minimize value)
Logical map of volume determinations
The central bank of the provident fund accounts for the loan lines, which verify the four conditions below, each of which calculates a level, the final approval level, which is the lowest of the four results, which is the key point where many people measure their vulnerability to error. 1. Multiply of account balances: calculated on the basis of the provident fund account balance x multiple (the most common domestic algorithm); (c) local ceiling: single ceiling, couple ceiling, rigid ceiling。
The central bank of the provident fund accounts for the loan lines, which verify the four conditions below, each of which calculates a level, the final approval level, which is the lowest of the four results, which is the key point where many people measure their vulnerability to error. 1. Multiply of account balances: calculated on the basis of the provident fund account balance x multiple (the most common domestic algorithm); (c) local ceiling: single ceiling, couple ceiling, rigid ceiling。
In addition, there are additional constraints: overdue letters, defaults on the provident fund, insufficient time to pay and outstanding loans to the provident fund are directly reduced or cannot be applied for. We're going to break it down on a case-by-case basis。
Reference table for mainstream urban provident fund loan ceilings
Comparison of the provident fund ceiling
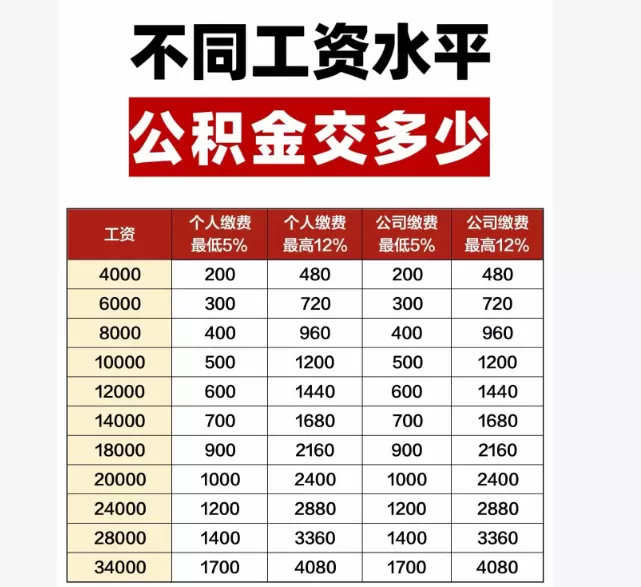
Note: the table below provides a common reference standard for most cities in the country, which will be adjusted separately by the local prscs; some cities will separate the first and second sets and some cities will support families with children. • the maximum loan limit for both spouses (thousands of dollars)
(a) 1 and this is a rigid ceiling, which cannot be exceeded even if you have more balances and higher incomes。
First algorithm: multiplication of account balances (most commonly used)
Figure for multiplication of balances
The multiplication of balances is the method used by the vast majority of cities to calculate the amount: loanable amount = provident fund account balance x multiples common range: 10 times, 15 times, 20 times, with a few cities having a maximum of 25 times; with a lower balance limit, the balance is too few to limit directly。
The multiplication of balances is the method used by the vast majority of cities to calculate the amount: loanable amount = provident fund account balance x multiples common range: 10 times, 15 times, 20 times, with a few cities having a maximum of 25 times; with a lower balance limit, the balance is too few to limit directly。
Examples are: a policy multiplier of 15 times a given location, with an employee provident fund account balance of 40,000 yuan, loanable amount = 40000 x 15 = 600,000 dollars; if the local individual ceiling is only 500,000, then eventually only 500,000。
Important details: 1 or part of the city requires six months of continuous contributions / 12 months to be calculated using a multiple of the balances; 2 or the accumulated contributions, many of which are not accounted for in the account balance; 3 or the account balances have become smaller after processing the drawings (rents, renovations) that directly affect the loan line。
Second algorithm: the method of repayment capacity coefficients (basic of contribution)
Measurement of repayment capacity
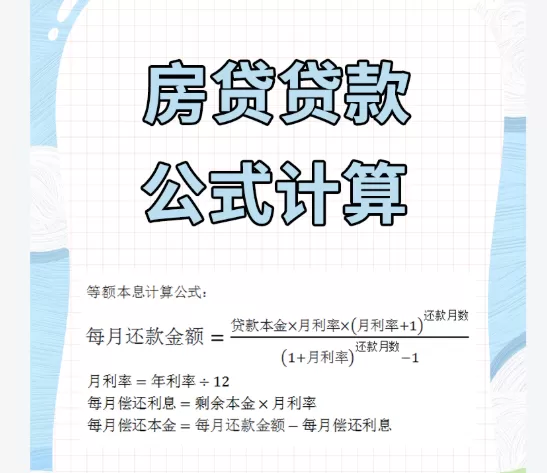
This algorithm is limited in terms of repayment capacity and prevents excessive monthly supply from affecting life. The formula varies slightly from one place to another. It is a common version: loanable amount = (monthly contribution base x repayment factor - other monthly liability monthly)。
This algorithm is limited in terms of repayment capacity and prevents excessive monthly supply from affecting life. The formula varies slightly from one place to another. It is a common version: loanable amount = (monthly contribution base x repayment factor - other monthly liability monthly)。
For example: employee monthly contribution base of $800, local repayment factor of 0. 4, no other loans, planned loan of 30 years, 3. 1% provident fund interest rate of maximum monthly allowance of = 8000 x 0. 4 = 3200 yuan, and 30 years equivalent monthly principal and interest rates, inversely total loanable. If only 400,000, even a multiple balance count, 600,000, a ceiling of 500,000, and a final amount of 400,000。
Key reminders: the monthly pay basis is the payroll base declared by the provident fund and can be found in the provident fund app。
A third algorithm: limit on the proportion of the house price, cap on the loan to which the down payment corresponds
Description of the down payment ratio
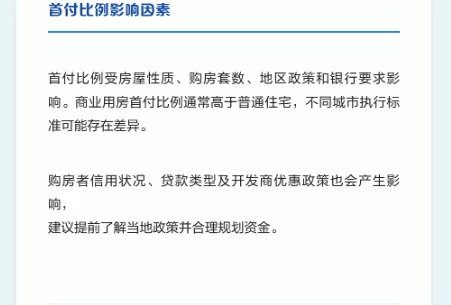
Provident fund loans also have a down payment requirement, and the amount of the loan cannot exceed the ratio of the total house price x loan. First suites: most municipal provident fund loans up to 70 per cent of the loanable price (30 per cent down payment); second suite: up to 50 per cent - 60 per cent of the loan price (40 per cent down payment - 50 per cent)。
Provident fund loans also have a down payment requirement, and the amount of the loan cannot exceed the ratio of the total house price x loan. First suites: most municipal provident fund loans up to 70 per cent of the loanable price (30 per cent down payment); second suite: up to 50 per cent - 60 per cent of the loan price (40 per cent down payment - 50 per cent)。
For example, the total price of the new house is 1 million, the first suite is 30 per cent, the down payment is 30 per cent, and the loan is up to 700,000; and even the balance, income and ceilings support 800,000, with the maximum mortgage of 700,000. The second-hand room is subject to an additional assessment: the central provident fund centre accounts for the value of the assessment, not the gross price, which is generally lower than the total price, which is the reason why the second-hand room can easily shrink。
Vii. Compensation of multural contributions
Map of combined pension calculation
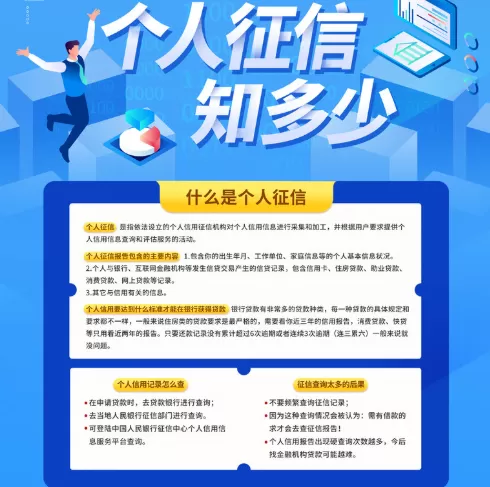
There are three types of situations in which a large number of purchasers are both husband and wife who pay the provident fund: 1 in which the couple is in a continuous and regular state and there is no record of the provident fund loan: the balance is combined and the maximum amount of the couple is applied; 2 in which only one party pays the provident fund: only the balance of one of the parties, the base amount, the individual limit; 3 in which any of the parties previously had a provident fund loan outstanding: the vast majority of municipalities are prohibited from applying again for the provident fund loan and must settle it before they can reapply。
There are three types of situations in which a large number of purchasers are both husband and wife who pay the provident fund: 1 in which the couple is in a continuous and regular state and there is no record of the provident fund loan: the balance is combined and the maximum amount of the couple is applied; 2 in which only one party pays the provident fund: only the balance of one of the parties, the base amount, the individual limit; 3 in which any of the parties previously had a provident fund loan outstanding: the vast majority of municipalities are prohibited from applying again for the provident fund loan and must settle it before they can reapply。
Corrected by error: not two persons are paid up to double a certain amount and the balance, income, house price and ceiling are still to be met with minimum value. For example, the sum of the couple's balance is 30,000, 20 times the value of the sum, i. E. 600,000; however, the local upper limit is 500,000, and ultimately only 500,000。
Quick self-examination: what would directly reduce the level of the provident fund loan or not be available
Refusal of provident fund loans
List of reductions. Most cities require payment in full and on a continuous basis for more than six months, and some require 12 months, with interruptions that are not directly eligible; 2/ the provident fund has a record of withdrawals: rental, major repairs reduce the account balance and lower the amount calculated by multiple balances; 3/ undesired letters of credit: continuous, current overdue, reduced or directly rejected; 4/ other significant liabilities under the name: consumer loans, high monthly payments, taking up the repayment ratio, and reducing the amount of the public provident fund that can be repaid; 5/ previous provident fund loans are overdue and the public provident fund loan record is not closed; 6/ purchase of a third set and more housing: most cities stop public capitalization loans。
List of reductions. Most cities require payment in full and on a continuous basis for more than six months, and some require 12 months, with interruptions that are not directly eligible; 2/ the provident fund has a record of withdrawals: rental, major repairs reduce the account balance and lower the amount calculated by multiple balances; 3/ undesired letters of credit: continuous, current overdue, reduced or directly rejected; 4/ other significant liabilities under the name: consumer loans, high monthly payments, taking up the repayment ratio, and reducing the amount of the public provident fund that can be repaid; 5/ previous provident fund loans are overdue and the public provident fund loan record is not closed; 6/ purchase of a third set and more housing: most cities stop public capitalization loans。
Ix. Online self-help measurement channels, official precision access points
Shapes: cut-off for ppp measurement
The manual calculations are only an estimate, the accuracy of which is based on the central provident fund system,3 free of charge for three official sources: 1 — the network of officials of the local housing provident fund management centre, with an in-house loan calculator; 2 — the national provident fund small program, the local provident fund app — with a key measurement after login; 3 — payment of treasures / micro-credit fund panels, with some municipalities operating the measurement function; 4 — the under-line provident fund window, with identification cards to pre-screen staff。
The manual calculations are only an estimate, the accuracy of which is based on the central provident fund system,3 free of charge for three official sources: 1 — the network of officials of the local housing provident fund management centre, with an in-house loan calculator; 2 — the national provident fund small program, the local provident fund app — with a key measurement after login; 3 — payment of treasures / micro-credit fund panels, with some municipalities operating the measurement function; 4 — the under-line provident fund window, with identification cards to pre-screen staff。
Reminder: on-line third-party fund measurement micro-processes, the results are for information purposes only and cannot be used as a basis for approval, subject to approval by the central provident fund。
X. Possible appropriate appropriate approaches
Summary of methodology for drawdowns
(a) refrain from making arbitrary withdrawals of the provident fund: keep account balances as much as possible for 1-2 years before buying a house。
(a) refrain from making arbitrary withdrawals of the provident fund: keep account balances as much as possible for 1-2 years before buying a house。
Xi. Summary of the full text
Thinking chart for measuring the volume of stocks
The core logic for calculating how much they can borrow is a four-fold limitation, with a minimum value: the number of account balances, the ability to repay (the base figure), the proportion of house price loans, the local ceiling. The table first identifies the maximum amount of the first set of two sets of ceilings for single persons and couples, then calculates it using the multiple-balance formula and the income-repaying formula, respectively, and then compares it with the first-payment ratio of the house price, the smallest of the four values being the advance amount of the available loan。
The core logic for calculating how much they can borrow is a four-fold limitation, with a minimum value: the number of account balances, the ability to repay (the base figure), the proportion of house price loans, the local ceiling. The table first identifies the maximum amount of the first set of two sets of ceilings for single persons and couples, then calculates it using the multiple-balance formula and the income-repaying formula, respectively, and then compares it with the first-payment ratio of the house price, the smallest of the four values being the advance amount of the available loan。
It is important to bear in mind that urban policies vary widely, with multiples, repayment factors, ceilings and down payment rates being developed by local provident fund centres, and that the internet-based common formula can only be used to estimate, with final approval being subject to review by the provident fund management centre. Joint spousal loans may be combined with a higher maximum amount, provided that both parties are regularly and continuously paid, while the amount is directly affected by default, excessive withdrawals, letters of credit and high liabilities. Before buying a house, it is recommended that three to six months in advance of checking the status of the provident fund, account balances and using the official calculator to avoid depositing a down payment before discovering that the amount of the stock is insufficient, causing passivity. Rationally planned stocks and low-interest loans can significantly reduce interest expenditure on housing loans。










