


How much for a year? 2026 guidelines for the settlement of insurance premiums
One, what's the risk? Why do you have to buy it
Base map for risk reduction
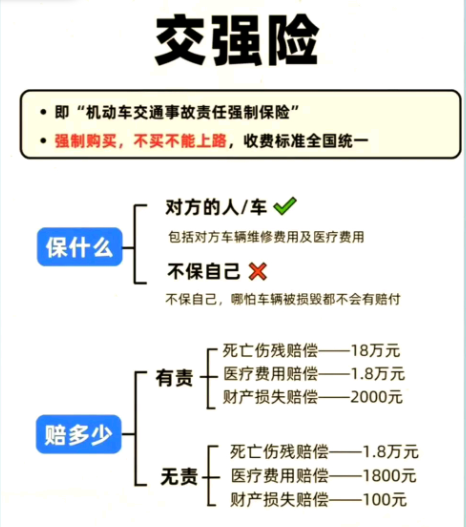
The compulsory liability insurance for motor vehicle accidents, which is the type of insurance that the national law imposes on all motor vehicles that must be insured, is a statutory liability risk, cannot be boarded without having to pay for them, cannot be checked year after year, is found to have been seized, and is subject to a fine of two times the premium. Many drivers are prone to confusion between strong risk and commercial risk: the risk only compensates the other victim of the accident and does not compensate for the loss of his own vehicle and his own vehicle; the commercial risk is voluntarily purchased to supplement the portion of the insurance that is not covered by the strong risk. The core purpose of the risk insurance is to ensure that third-party victims of traffic accidents, even if the owner is unable to pay compensation, are paid first within the limits and reduce the social risk of accidents. The basic premium on risk insurance is unified throughout the country, with insurance companies having no private bargaining power and, ultimately, the premium is high and low, determined mainly by the model of the vehicle, the annual record of liability risk, and the floating programme in the area。
The compulsory liability insurance for motor vehicle accidents, which is the type of insurance that the national law imposes on all motor vehicles that must be insured, is a statutory liability risk, cannot be boarded without having to pay for them, cannot be checked year after year, is found to have been seized, and is subject to a fine of two times the premium. Many drivers are prone to confusion between strong risk and commercial risk: the risk only compensates the other victim of the accident and does not compensate for the loss of his own vehicle and his own vehicle; the commercial risk is voluntarily purchased to supplement the portion of the insurance that is not covered by the strong risk. The core purpose of the risk insurance is to ensure that third-party victims of traffic accidents, even if the owner is unable to pay compensation, are paid first within the limits and reduce the social risk of accidents. The basic premium on risk insurance is unified throughout the country, with insurance companies having no private bargaining power and, ultimately, the premium is high and low, determined mainly by the model of the vehicle, the annual record of liability risk, and the floating programme in the area。
Ii. Basic premium price tables for vehicles with high risk (usb)
Tables of high-risk prices
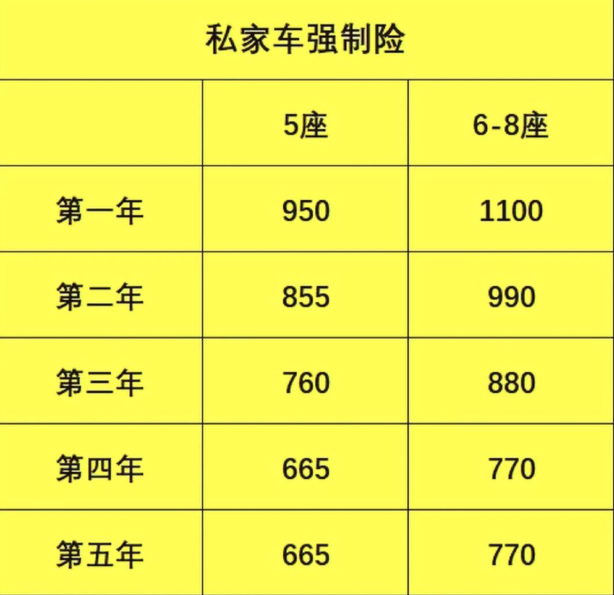
Note: the following table shows the basic price of insurance coverage for the first year of the new vehicle, and the price of subsequent renewal will fluctuate according to the risk record。
Table
| Type of vehicle | Breakdown specifications | First year basic premium ($/year) |
|---|---|---|
| Home buses | Below 6 (5 sedans, suv) | 950 |
| Home buses | 6 and above (7 suv, mpv) | 1100 |
| Enterprise non-operational buses | Below 6 | 1000 |
| Enterprise non-operational buses | 6-10 seats | 1190 |
| Truck, non-operational | Up to 2 tons | 1200 |
| Operation of taxis | Below 6 | 1800 |
| Truck operation | Up to 2 tons | 1850 |
| Motorcycle | 50cc and below | 80 |
| Motorcycle | 50cc-250cc | 120 |
| Motorcycle | 250cc and above, side three | 400 |
The vast majority of private cars are five domestic cars, with the first year at a high risk benchmark of $950, seven domestic cars at $1,100, and two of the most frequently searched by the owner。
Iii. Equivalent premium formulae, description of regional floating programmes
A logical illustration of how the premium will float
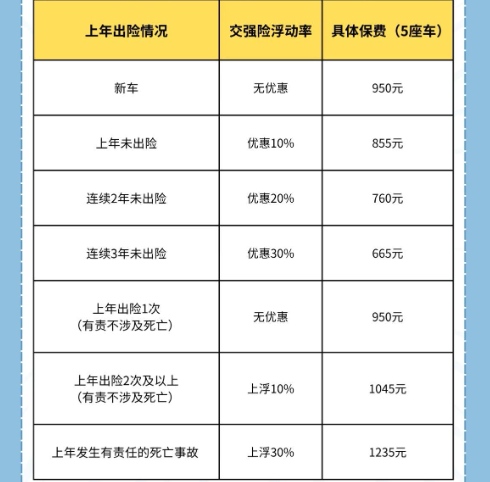
The formula for the calculation of the final premium for risk-taking: contributions for risk-taking = base premium x (1 + rate floating factor) national financial supervisors... The country is divided into five regional floating programmes, with most of the provinces of jiangsu, shanghai, zhejiang, anhui, shandong, guangdong, sichuan, chongqing, henan, hubei and hunan being part of the e programme and the applicable version of jiangsu's carowners:
The formula for the calculation of the final premium for risk-taking: contributions for risk-taking = base premium x (1 + rate floating factor) national financial supervisors... The country is divided into five regional floating programmes, with most of the provinces of jiangsu, shanghai, zhejiang, anhui, shandong, guangdong, sichuan, chongqing, henan, hubei and hunan being part of the e programme and the applicable version of jiangsu's carowners:
- Unaccompanied incidents in the previous year: 10 per cent
- 2 consecutive years of no-accountable accident: 20% down
- Unaccompanied accidents of 3 consecutive years and above: downward 30%
- Previous year 1 responsible accident (no death): floating 0%, return to base price
- Previous year 2 and above responsible incidents: up 10%
- In the last year, there was an incident of responsible death: up 30% of the national financial inspector...
Example:
- 3 consecutive years without risk: 950 x 0. 7 = 665 yuan
- One case of liability in the previous year: $950
- Responsible death in the previous year: 950 x 1. 3 = 1235 yuan
Focus: irresponsible accidents don't affect the flaming of risk. You're completely blamed. Not your risk。
Iv. Paying the maximum amount of the risk, knowing how much to pay. Money
Many drivers only care about how much they pay for them
It's not clear, there's a total liability limit of 200,000, which can't be combined... Death and disability limit: $180,000 (burial, disability, accident, nursing, psychiatric relief, etc.)
It's not clear, there's a total liability limit of 200,000, which can't be combined... Death and disability limit: $180,000 (burial, disability, accident, nursing, psychiatric relief, etc.)
The maximum amount of property paid was $2,000, and in the event of a major accident, compensation was far from sufficient, so that the general owner was supplemented by a third party commercial risk。
V. Key factors influencing high-risk prices, what increases, what savings money
Comparison of premium changes in risk or not
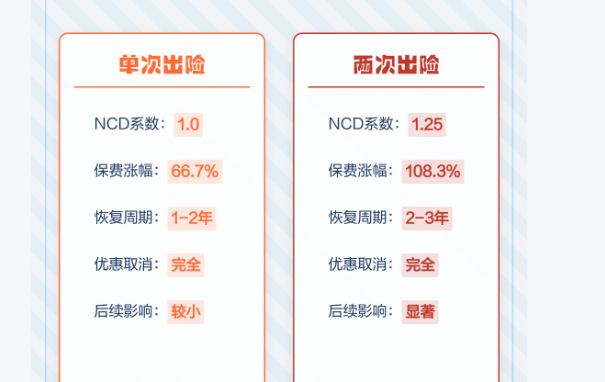
First, the nature of vehicle usage. The same 7-car, which is not operated at home, is $1,100, and if it is changed to the nature of internet vehicles, the premium will rise directly to the operating bus standard and the price will rise significantly. Second, there is a record of responsible traffic accidents, which are at the core of the price change for renewal. As long as the traffic police hold you responsible, you will be recorded in the record of risk-taking and risk-taking, with a discount of zero or upward; the accident for which the other party is solely responsible has no effect on the payment of the premium. Third, a second-hand car. Once the vehicle has been transferred, the margin of exposure is cleared and recalculated to the base premium. For example, the original owner was unharmed for three consecutive years at $665, transferred to you, went straight back to $950 in the second year. Fourth, release. The insurance was not renewed in time for the expiration of the risk insurance period, and the insurance was reinsured after the release, as well as the previous no-risk benefit and the base price was restored。
First, the nature of vehicle usage. The same 7-car, which is not operated at home, is $1,100, and if it is changed to the nature of internet vehicles, the premium will rise directly to the operating bus standard and the price will rise significantly. Second, there is a record of responsible traffic accidents, which are at the core of the price change for renewal. As long as the traffic police hold you responsible, you will be recorded in the record of risk-taking and risk-taking, with a discount of zero or upward; the accident for which the other party is solely responsible has no effect on the payment of the premium. Third, a second-hand car. Once the vehicle has been transferred, the margin of exposure is cleared and recalculated to the base premium. For example, the original owner was unharmed for three consecutive years at $665, transferred to you, went straight back to $950 in the second year. Fourth, release. The insurance was not renewed in time for the expiration of the risk insurance period, and the insurance was reinsured after the release, as well as the previous no-risk benefit and the base price was restored。
Vi. Strengthening institutions, industrial care
On-line insurance, on-line insurance, under-line insurance
There's a lot of access to insurance, prices are uniform, and there's no a insurance company cheap, b insurance company expensive, but value-added services are offered differently. Channel one: the network of insurance companies, official apps, micro-mails, public service lines, which support renewals, quotations, e-insurance policies, are now widely available throughout the country, and in most areas paper labels are not required. Channel two: 4s stores, car repair shops, new cars are on fire; channel three: insurance clerks lined up。
There's a lot of access to insurance, prices are uniform, and there's no a insurance company cheap, b insurance company expensive, but value-added services are offered differently. Channel one: the network of insurance companies, official apps, micro-mails, public service lines, which support renewals, quotations, e-insurance policies, are now widely available throughout the country, and in most areas paper labels are not required. Channel two: 4s stores, car repair shops, new cars are on fire; channel three: insurance clerks lined up。
Important reminders: 1 for a period of one year, with early renewal prior to expiry, to avoid being released from safety; 2 for not returning from insurance, which would be met only if the vehicle was scrapped, moved out and the vehicle was lost; 3 for the insurance policy to accompany the vehicle and to provide information on the policy when the risk was reported。
Vii. The different between strengthening and through risk, why it's not enough to risk
Increased risk exposure + commercial triple risk coverage figure
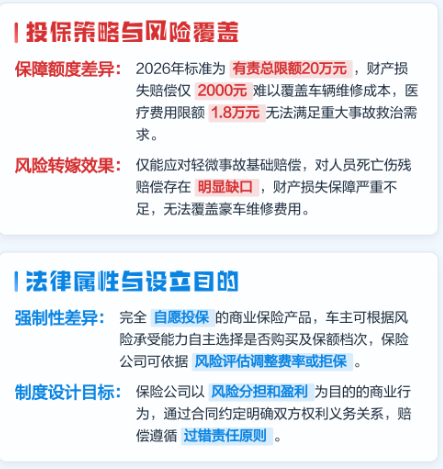
Strong insurance is compulsory, low-level, sub-stricted, and property is limited to 2000 yuan. Take a scene: you hit a limo car with $50,000 for each other to fix it, and you paid $2,000 for the insurance, leaving $48,000 to be paid for by the owner; if you hit a pedestrian, more than $18,000 for serious injuries, the excess would have to be paid by the owner. Commercial third-party liability insurance is voluntary, with a premium of 1 million, 2 million, 3 million and 5 million available to cover the part of the risk that cannot be fully recovered. It is recommended that private cars be equipped with more than 2 million three-person insurance to avoid the risk of large-scale accidents, based on strong risk exposure。
Strong insurance is compulsory, low-level, sub-stricted, and property is limited to 2000 yuan. Take a scene: you hit a limo car with $50,000 for each other to fix it, and you paid $2,000 for the insurance, leaving $48,000 to be paid for by the owner; if you hit a pedestrian, more than $18,000 for serious injuries, the excess would have to be paid by the owner. Commercial third-party liability insurance is voluntary, with a premium of 1 million, 2 million, 3 million and 5 million available to cover the part of the risk that cannot be fully recovered. It is recommended that private cars be equipped with more than 2 million three-person insurance to avoid the risk of large-scale accidents, based on strong risk exposure。
Viii. Common error zones. Many drivers get it wrong
Coptics
It can always be broken without risk. Most of the regions currently have the maximum flooring ceiling of 30 per cent, 5 private cars have the lowest of $665 and will not continue to decline prices. Zone two: small scratches of responsibility and high risk increases. Irresponsible accidents do not count as exposure and do not increase prices. There is no other way. The third-party victim was only compensated for the risk, and the loss of the vehicle, its personnel, was not covered. Wrong area four: different insurance companies offer different prices. The basic premium countries are uniform and priced at the same price, and the difference is limited to value-added services such as car washes and proxy annual checks. Mistake five: second-hand vehicles are transferred and the premium is retained. Post-occupancy floating factor is replaced and the base price is restored。
It can always be broken without risk. Most of the regions currently have the maximum flooring ceiling of 30 per cent, 5 private cars have the lowest of $665 and will not continue to decline prices. Zone two: small scratches of responsibility and high risk increases. Irresponsible accidents do not count as exposure and do not increase prices. There is no other way. The third-party victim was only compensated for the risk, and the loss of the vehicle, its personnel, was not covered. Wrong area four: different insurance companies offer different prices. The basic premium countries are uniform and priced at the same price, and the difference is limited to value-added services such as car washes and proxy annual checks. Mistake five: second-hand vehicles are transferred and the premium is retained. Post-occupancy floating factor is replaced and the base price is restored。
Ix. Implications of imprisonment of risk
This is the first map of the penalties imposed, and the vehicle cannot attend the annual inspection
(c) in the event of a traffic accident, all compensation will be paid to the owner, without insurance, and the financial risk is extremely high; it is imperative that insurance be renewed in a timely manner and that there be no complacency。
(c) in the event of a traffic accident, all compensation will be paid to the owner, without insurance, and the financial risk is extremely high; it is imperative that insurance be renewed in a timely manner and that there be no complacency。
X. Comprehensive summary
In the end, we have to get to the bottom of this
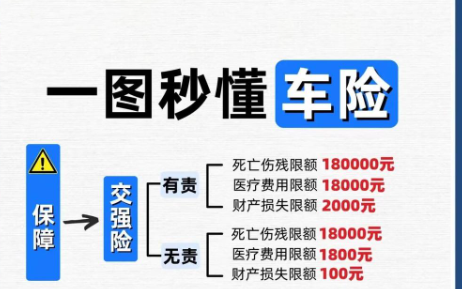
The initial base price of 5 private cars is 950 yuan per year, the base rate of 6 and above is 1100 yuan per year, and a separate base rate is applied for motorcycles, trucks and operating vehicles. The price of the eventual renewal of the risk exposure is up to 30 per cent discount for years of continuous safety, elimination of the premium for liability and rise in insurance premiums for serious accidents, based on the region's floating programme, annual record of liability risk。
The initial base price of 5 private cars is 950 yuan per year, the base rate of 6 and above is 1100 yuan per year, and a separate base rate is applied for motorcycles, trucks and operating vehicles. The price of the eventual renewal of the risk exposure is up to 30 per cent discount for years of continuous safety, elimination of the premium for liability and rise in insurance premiums for serious accidents, based on the region's floating programme, annual record of liability risk。
Strong risk insurance is the minimum third-party guarantee, with a total liability limit of 200,000 and a limited amount of sub-payments. All insurance companies are unified at high risk, and there is no low risk insurance. Passage of second-hand vehicles and high-risk bail will result in the recovery of the base premium. Strong risk insurance is a mandatory requirement for access, timely renewal of insurance and reduced liability for safe driving, which avoids a penalty deduction and saves an annual premium, combined with commercial triple risk insurance, in order to create full vehicle insurance coverage。










