


Title: depreciation adjustments for fixed assets: how do enterprises comply
I. Background to the adjustment for the payment of remittances
Depreciation of fixed assets is an important factor in the financial management of enterprises. In practice, however, for a variety of reasons, the enterprise may experience an inaccurate calculation of depreciation of fixed assets, requiring an adjustment in the remittances. This paper will focus on this theme and explore how enterprises can comply with the depreciation adjustments for fixed assets。
Method of calculating depreciation of fixed assets
Depreciation of fixed assets is calculated mainly by straight-line method, accelerated depreciation method, workload method, etc. An enterprise should choose the appropriate depreciation method according to the nature and use of the fixed asset. For example, for equipment with longer useful life, a straight-line approach could be chosen, while for electronic equipment that is up to date, accelerated depreciation could be chosen。
Iii. Steps for colonial corrections
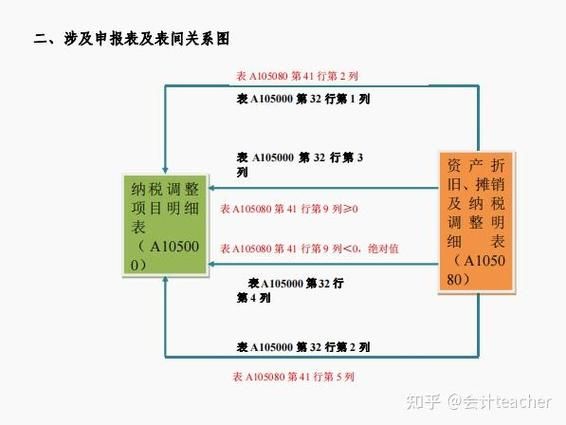
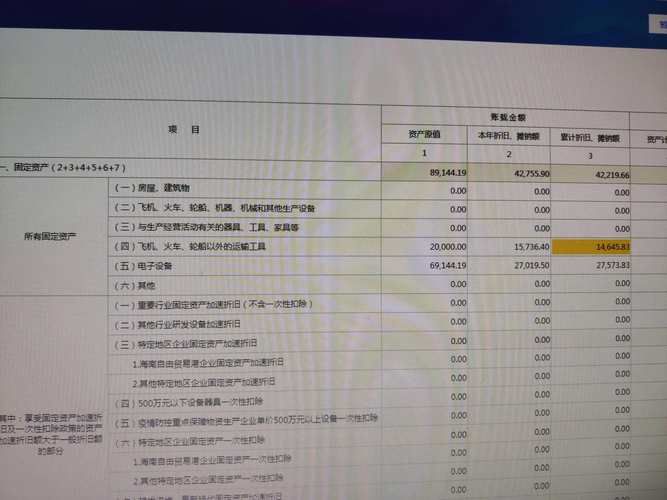
1. Check the validity of depreciation of fixed assets. First, the accuracy of parameters such as the recorded value of fixed assets, the expected useful life, residual value ratio, etc. Second, the applicability of the depreciation method is recognized。
Calculate the amount of the adjustment. Based on the results of the inspection, an adjustment for depreciation was calculated. If depreciation is found to be excessive, the depreciation cost should be reduced; otherwise, the depreciation cost should be increased。
3. Preparation of adjustment entries. Based on the amounts adjusted, appropriate accounting entries are prepared, such as debiting “cumulative depreciation” to be credited to “fixed assets”。
4. Submission of applications for adjustments. Adjustments to the entries and related information are submitted to the tax authorities for adjustment of the remittances。
Iv. Notes
Compliance. When adjusting for depreciation of fixed assets, the relevant laws and regulations must be complied with to ensure compliance。
2. Timeliness. When depreciation errors in fixed assets are detected, adjustments should be made in a timely manner to avoid affecting the financial position of the enterprise。
Transparency. The adjustment process should be transparent and ensure that tax authorities and internal auditors are aware of the reasons and process for the adjustment。
V. Common questions and answers
Q: can enterprises adjust their own depreciation of fixed assets
Response: an enterprise can adjust depreciation of fixed assets on its own the basis of actual circumstances, subject to the requirements of relevant laws and regulations and ensuring compliance with the adjustment。
Q: does adjusting depreciation of fixed assets affect the tax burden of enterprises
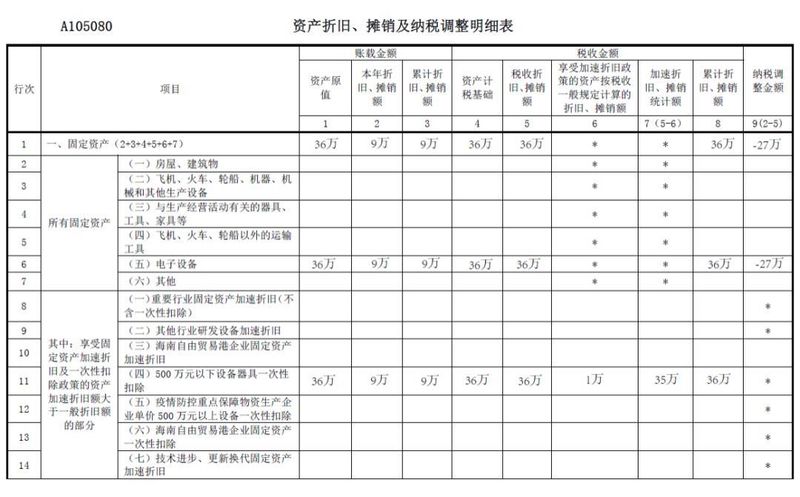
Response: adjustments to depreciation of fixed assets affect the tax burden of the enterprise. If the adjusted depreciation cost increases, the tax burden of the enterprise may be reduced and vice versa。
Summary
Depreciation adjustments for fixed assets are an important element of the financial management of the enterprise. Enterprises should operate in strict compliance with laws and regulations and accounting standards to ensure compliance and accuracy of adjustments. Through this presentation, it is hoped that enterprises will have a better understanding and mastery of the method of accounting for depreciation of fixed assets。
This paper was compiled and published by the state services limited。
• previous article: how to identify beijing trademark transfer agents in the next issue: sme fiscal services offers: key elements for discovering reasonable choices









