• financial remittance app news — in 2026, there was a highly contradictory set of market phenomena in the gold market, with geo-risks and fiscal pressures that would have provided a strong shield for gold, but the opportunity costs associated with continued high real interest rates continued to stifle the price of gold。
The focus of market attention has been on whether real interest rates will continue to rise again, with many institutions judging that interest rates are already limited and that the largest profit factor for gold may recede。
Interest rates are expected to reverse, and the price of gold is under great pressure
The market’s monetary policy is expected to undergo a sharp reversal this year, with the market generally pegging the fed’s downfalls one to two times at the beginning of the year, and with repeated inflation data, the market has begun trading interest rate hikes. Jeffrey calculated that the return on the ten-year inflation reserve national debt rose from 1. 94 per cent to 2. 41 per cent at the beginning of 2026, with the expected rapid reversal of the price falling by about 25 per cent from the height of the period。
Even in the face of such a strong space, the gold is holding up at a critical level of $4,000 per ounce. Data from the world gold association show that the july price of gold has remained almost at a shock near $4027. Even if the real rate of return on the european german government’s debt was set at a 15-year high, europe’s gold etf would still be inflow enough to reflect the market’s bottom-up buying power, and the gold would have absorbed most of the profit-making shock from opportunity costs。
Institutional perspective: no interest rate, no profit
In its latest report, the bca research institute indicated that the most difficult phase of real interest rate pressure on gold was probably over. The agency’s chief strategist for large commodities, roukaya ibrahim, has stated that a new round of gold booms does not require a downfall operation by the fed’s chairman, as long as real interest rates continue to move up with the end of the dollar。
This logic is further supported by the reset history of jeffrey, where the subsequent movement of gold after the real interest rate shock does not depend entirely on the absolute value of the interest rate, and the core depends on whether the kinetic energy of the movement of the interest rate fades. The current re-pricing of monetary policy in the market is largely on the ground, and once the upward pressure on real interest rates has eased, gold and gold mining stocks will have a rehabilitation base。
The structure of the ledogane is not wavering
While the wind is expected to cool down the price of gold, the underlying logic underpinning gold remains solid. Global multinational central banks continue to build up their gold reserves, and de-dollarization, fiscal distress in countries, and global geographical uncertainty remain long-term markets. According to the bca research institute, while central bank purchases are difficult to boost again, official demand for gold purchases still holds the bottom line。
The drive of inflation towards gold prices also needs to be seen in a dialectic. According to the world gold association, the boosting effect of inflation will only be fully released if inflation does not rise, with 4 per cent in excess, accompanied by a fall in real interest rates, a weakening of the dollar or an increase in the risk of recession。
Taken together, large amounts of gold do not require extreme scenarios such as a massive economic recession and monetary emergency easing, and markets will turn the tide as long as the negative factors that press gold prices do not continue to deteriorate. After a heavy opportunity cost shock, gold may have reached a critical turning point, and if real interest rates are confirmed to peak, the largest profit margin in the past will turn into the core driving force driving gold prices。
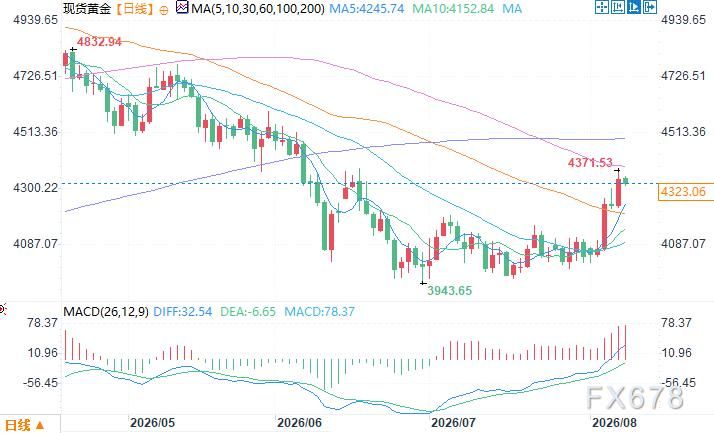
Cash gold day line from: easy to communicate
Beijing time, 10:18 august, spot gold. Division
Please unlock the golden wall