I've recently seen news like this:
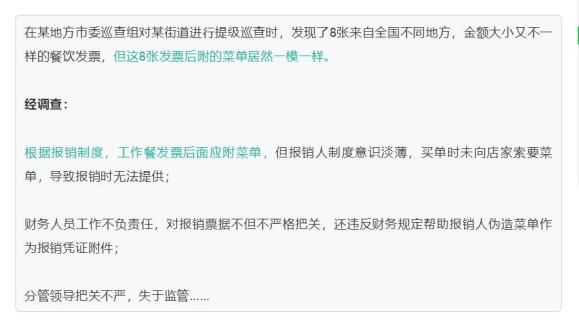
Without exception, we find that a number of companies have also requested that no one with a menu be reimbursed。
Do you need a menu to cover the cost of food? How do you specify? How do you account for the cost? Can full pre-tax deductions be made? Do you want to pay a tax on personal food reimbursement? Let's get this over with
The tax authorities are clear
There's no menu for food reimbursement
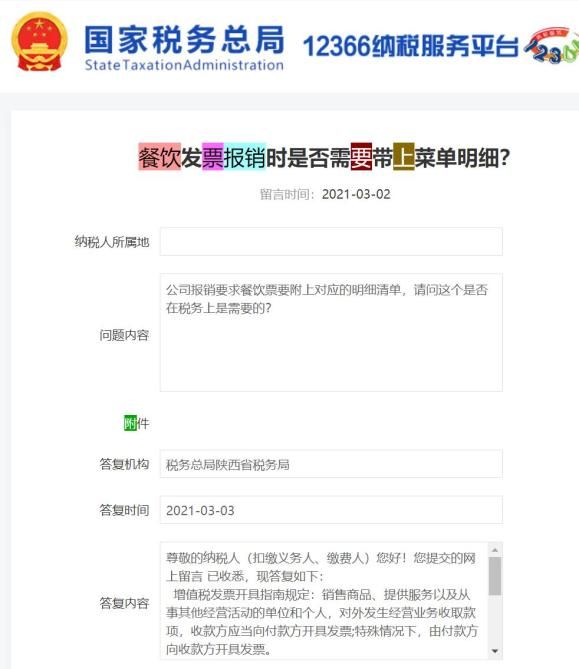
As can be seen from the above-mentioned responses from the tax administration, there is no express tax provision whereby the cost of meals must be covered by a menu。
The pre-employer income tax credit scheme (irs 84) provided for a menu to be attached to the reimbursement of the cost of meals, but the document has been repealed by decree no. 23 of the national tax administration authority. The current tax laws and regulations are no longer required, so the food and food bills are issued without the need for detailed menus。
How do you account for the meals
Can you deduct the tax
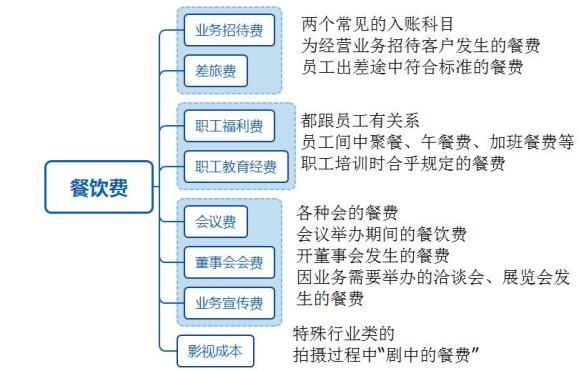
When it comes to meals, “business hospitality” comes to mind, but not all meals go to business hospitality。
Because of the nature of the business, the personnel reimbursed, etc., the cost of meals is different
Based on taxes according to article 36, the amount of taxes paid on loans purchased, catering services, day-to-day residential services and entertainment services may not be deducted from the amount of taxes paid。
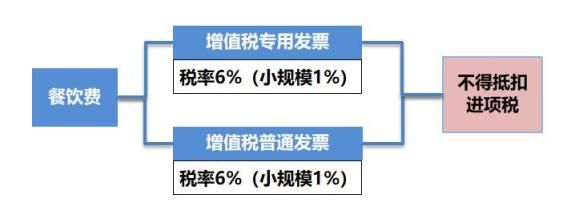
Note: 3 per cent less 1 per cent for small-scale taxpayers until 2022. 4. 1; 2022. 4. 1-2022. 12. 31, 3 per cent tax exemption。
Thus, catering services are non-deductible items and are not subject to deductions for vat-specific invoices。
Note:
What about obtaining special invoices for catering
In order to prevent the formation of suspense tickets, it is recommended that an in-kind tax transfer be made after certification or that no ticking credit be made directly on the ticking platform。
2. What about accommodation for meals on a single ticket
After full certification credit, the portion of the charge for catering is transferred out of the charge or the amount of the effective tax is changed directly on the ticking platform, with only the deduction for accommodation and not the deduction for catering。
How is the pre-tax deduction for meals regulated
Can you deduct the full amount
The cost of the meal is classified as business hospitality, is deducted by pre-tax deduction of 60 per cent of the amount incurred and is limited by 0. 5 per cent of the total income, is excluded from the actual ex-tax deduction of hospitality, and a table is summarized for study。
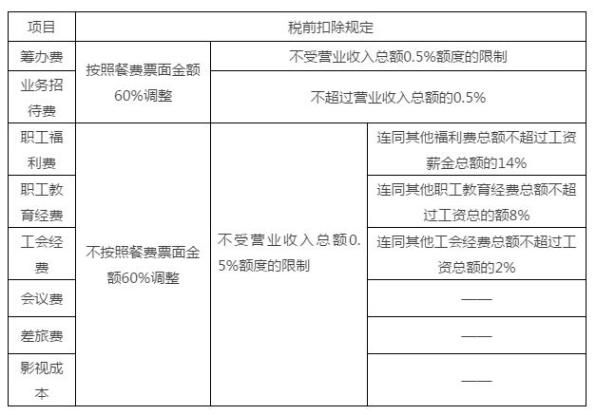
Note:
Accounting should not be accompanied by only one invoice, but also by supporting material supporting the authenticity of the catering costs。
1. The cost of meals is included in the costs of meetings, the board of trustees
The supporting documentation includes, but is not limited to, the title, time, venue, purpose and roster of participants, conference materials (agenda of the meeting, discussions, leadership speeches), vat invoices, live photographs or images of the meeting, payment water bills, etc。
2. Meals included in travel costs
The supporting documentation includes, but is not limited to, complete approval procedures, invoices for catering, invoices for field trips, and lists of personnel and personnel matching the number of personnel sent。
3. Catering charge to operating hospitality
The supporting documentation includes, but is not limited to, full clearance, details of hospitality, hospitality, value added tax invoices for catering。
4. Provision for meals is included in operating awareness
The supporting material includes, but is not limited to, full clearance procedures, promotional information, value added tax invoices for catering charges, etc。
5. Meals charged to welfare
The supporting material includes, but is not limited to, full clearance procedures, value added tax invoices for catering charges, etc。
6. The cost of meals is charged to employee education
The supporting material includes, but is not limited to, full clearance procedures, relevant training materials, value added tax invoices for catering fees, etc。
Distribution of meals to staff
Do you want to pay a tax
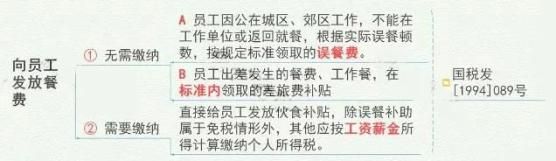
Note:
1. A staff member shall receive within standard travel allowance for meals, meals and other work-related expenses incurred on official business and shall not be subject to personal income tax。
This standard is not specific, and the enterprise itself sets the standard for travel allowance according to the business situation。
2. Pay attention to the distinction between a lunch allowance and an accident benefit:
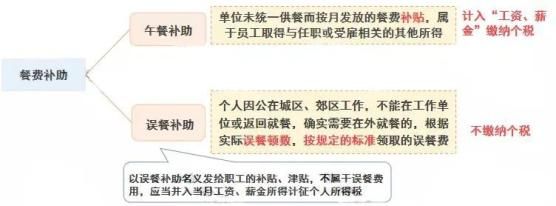
Annex: common invoices for meals
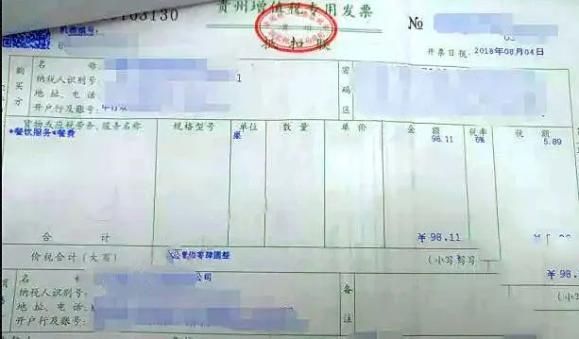
1. Catering services for vat-specific invoices
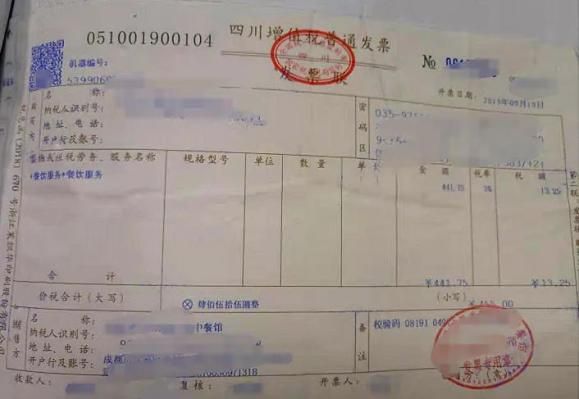
2. Catering services for general vat invoices
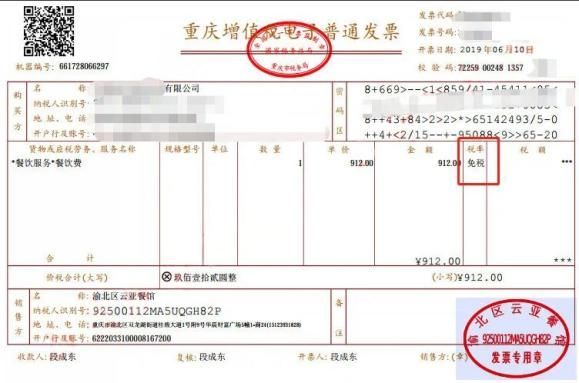
3. Catering services for vat electronic generic invoices
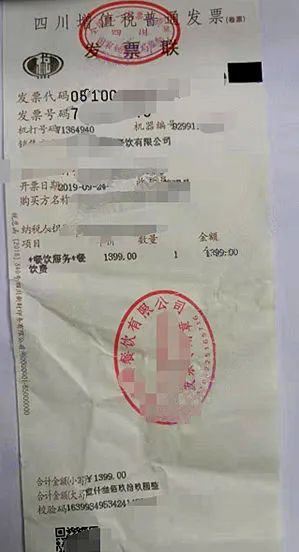
4. Catering services for general (roll) vat invoices
5. General purpose food invoices
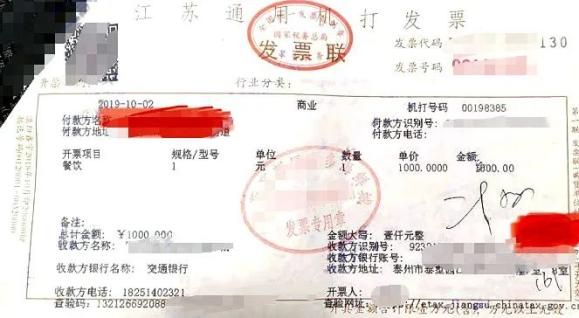
Catering services for generic flat invoices