


The bs flat-well ratio is an indicator of the cycling oxa pace model
The bs model first assumes that the price of the targeted secondary burn asset is subject to geometric brown movement and then constructs a risk-free combination of the item's assets and certificates with the benefit of a risk-free rate, thereby obtaining a differential equation, the solution of which is the price formula for the certificate. Since the bs model obtained an accurate resolution, the bs pricing model was generally more accurate than the mother-in-law. This resolution also allows for the sensitivity of the weighting value vis-à-vis the various influencing factors, such as delta, theta, etc., and is used to hedge. The bs model, however, can generally only price more conventional european-style standby licences (which result in only two proxies, with the result that they are in a state of constitutional loss), while the price of us-backed optics, path dependency, and so on, cannot be applied。
Trident tree rights pricing model
The didentary certificate pricing model, which was introduced as early as 1979, has become one of the most basic licensing methods in the financial community. Its basic point of departure is to assume that the movement of asset prices consists of a large number of small-scale binary movements, and to simulate the path that a continuous movement of discrete cold-forwarded jet jets can follow when the assets have been smoke-exhausted. At the same time, the price of the assets targeted for each node is obtained using the principle of arbitrage or risk-neutral pricing, and the price is then calculated from the moment of end-of-pipe cures, based on the profit and loss of the certificate. When the length of time between two consecutive steps of the diagonal tree model is zero, the model will accumulate to the bs model. It has the advantage of being relatively simple intuitive and can be priced for united states and other more complex licences, such as the united states-style reserve certificate and the bermudian certificate to be issued by the grand syndicate (the holder may exercise the right for a certain period of time during its life) as set out in the steel stock reform programme. However, it is not convincing to assume that the price of the assets targeted for a short period of time will move in two directions only with a particular probability。
Monte carlo model
The monte carlo simulation is a numerical method of obtaining the expected value of the licence through a random movement path to simulate the price of the asset at the mark, as well as a very broad method of licensing. It also uses risk-neutral pricing principles, the rationale of which is that, starting at the initial point in time with the target asset price, the mature value of a large number of the target assets is simulated by a hypothetical random path, the proceeds of each time the price is due are calculated, the average value is obtained and the valuation of the certificate is obtained at a no-risk interest rate. The advantage of the monte carlo approach is that it is relatively straightforward to apply it and can address many complex situations of gain or loss, especially path-dependent certificates (defunct earnings are dependent on intermediate prices). For example, it can rely on a certificate of reliance on the medium's path (which is an equity certificate, with a buy-back clause and a more complex position of profit or loss) and a right price. Strictly speaking, the certificates that appear in the securities market are path-dependent ones) to price. But it is not good at handling american certificates and often takes longer to calculate。
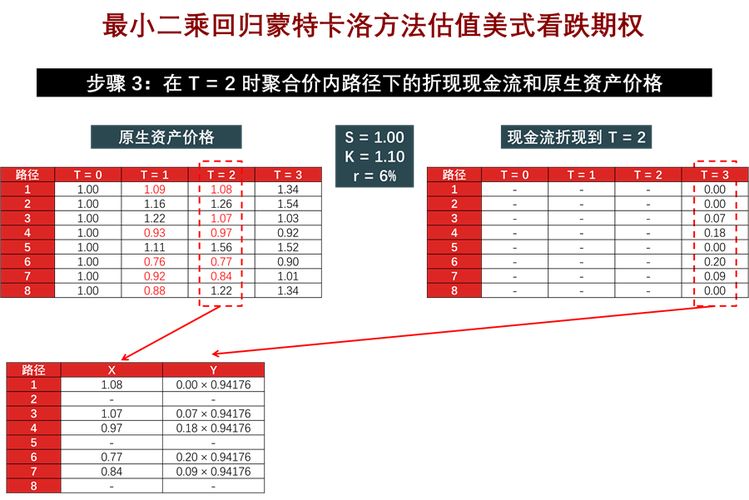
All three of these methods, using risk neutral or no arbitrage pricing principles, can be priced for conventional licences, with the bs model using a method of resolution, valuation being more precise, and the other two being broader. In response to the more complex provisions expected to be included in the subsequent roll-out, investors should analyse their impact on the maturities of the certificates in order to select the appropriate valuation method and seize investment opportunities in a timely manner。









